Financing: From an Old Fear to a Modern Financial Tool
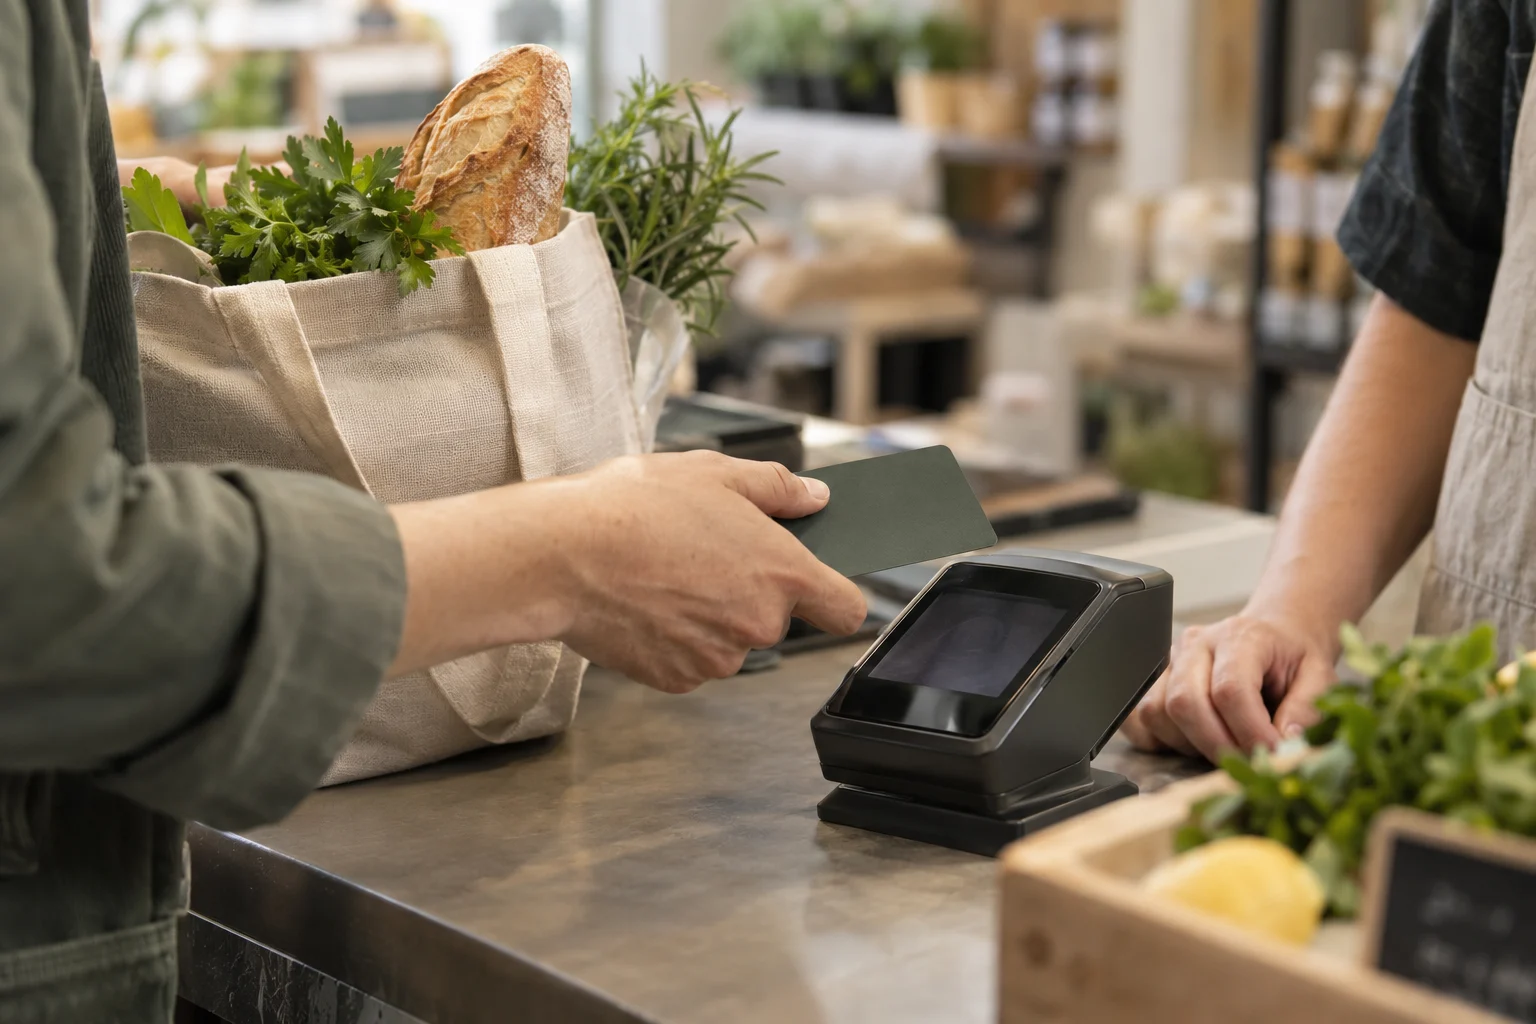
You are standing at the grocery store checkout, tap your credit card, collect the bags and go home. Almost nobody stops to think of that ordinary moment as financing. Legally, a standard credit-card transaction is not necessarily a “loan,” and the exact structure varies by country, card type and billing model. Economically, however, something very similar is taking place: you receive the goods today, while the cash leaves you later.
That is a useful place to begin, because financing is embedded in everyday life far more deeply than most of us realize. A mortgage is financing, of course. So is a student loan. Leasing is financing. Business credit, installment plans, revolving credit, borrowing against an asset and Buy Now, Pay Later all do the same basic thing in different forms: they move purchasing power across time. We receive financial capacity today that has not yet been fully funded by our current capital, and we commit future money in return.
Even so, in many families the word “debt” still carries something close to a moral warning. Do not borrow unless you have to. Do not buy what you cannot pay for. Save first, spend later. There is real logic behind that instinct. Earlier generations often lived in an environment with less accessible information, fewer ways to compare credit and periods in which interest rates or inflation could turn an apparently manageable commitment into a heavy burden. For many of them, caution around borrowing was not irrational. It was good financial survival instinct.
The environment has changed. Millennials and Gen Z came of age in a world where interest rates can be compared in minutes, financing alternatives can be reviewed in an app, mortgage terms can be modeled online and the effective cost of credit can be understood without scheduling a meeting at a bank. At the same time, credit has become psychologically less visible. Sometimes it barely feels like credit at all.
Buy Now, Pay Later is a good example. The U.S. Consumer Financial Protection Bureau describes the common version as a short-term loan, typically split into four payments and often offered without interest. According to Federal Reserve data, 16% of U.S. adults used BNPL in 2025, up from 10% in 2021. Among adults aged 18 to 29, usage reached 22%, and more than a quarter of users reported being late on at least one payment. That does not make the product inherently good or bad, but it does show how borrowing can become part of ordinary consumption without feeling like a formal financial decision. CFPB
A separate CFPB analysis found that more than three in five BNPL users had multiple such loans at the same time at some point. Each commitment can look small on its own. Together, they begin reserving a portion of future income before that income has even reached the bank account. CFPB
This is where the difference between good financing and bad financing actually begins. The distinction is not simply whether we used money that was not available to us in that exact moment. The more useful questions are what the money is being used for, what it costs, how long the obligation lasts and what it enables us to create in return.
Debt used to finance a long-lived asset is not the same as debt used to fund recurring consumption. Credit that allows a business to buy equipment that increases productive capacity is different from a loan repeatedly used to cover an operating loss no one has fixed. Financing education that may increase future earning power is a different decision from stretching out the payment for a consumer purchase that never really fit the household’s income in the first place.
The other side of the equation matters too. A blanket fear of financing can also be expensive. A business that refuses to use credit on principle may miss a profitable expansion opportunity. Someone who insists that every asset must be purchased only after the full price has been saved may discover that the asset itself became more expensive while they waited. A household holding a very large amount of cash purely to avoid all borrowing may be giving up other productive uses of its capital.
That is why “debt is bad” is just as weak a rule of thumb as “debt is cheap money.” Both replace analysis with a slogan.
A more mature approach is to treat financing as a tool. Every tool has a cost, a risk profile and situations in which it is appropriate. Good financing analysis asks about the total cost, whether the interest rate is fixed or variable, what happens if income falls, how large the repayment burden is relative to income, whether the thing being financed will remain useful longer than the debt itself and what alternative use the capital could have had.
Most importantly, it asks how the decision fits into the wider plan. Sometimes borrowing can be rational even when cash is available. Sometimes the opposite is true. The balance in the bank account, by itself, does not answer the question.
Earlier generations taught us, correctly, to respect debt. The generations that followed need to add another skill: learning to use financing without allowing it to become a lifestyle.
Good financing is not simply “money we do not have.” It is a deliberate choice about whose money to use, at what point in time, at what cost, and for what purpose.